Solutions · Microfinance Institutions
Ustawi for microfinance institutions.
- Gross portfolio
- TSh 902.3M · PAR30 4.2%
- Approval ladder
- Branch → committee → board
- Implementation
- Six steps to go-live
- Loan lifecycle
- Branch controls
- Portfolio monitoring
- Finance
- Compliance
Why Ustawi fits an MFI
- The full loan lifecycle out of the box — application to write-off
- A branch → committee → board approval ladder gated by loan amount
- Branch-scoped, role-based portfolio visibility
- BOT PAR30/PAR90 aging and 5-band classification generated live
- Both individual and group lending on the same engine
- A real double-entry GL under every loan event
What slows an MFI down
The pattern is the same across most microfinance institutions: the loan book lives in one place, the money in another, and the regulator's view has to be rebuilt by hand. Ustawi answers each of these directly.
Loan data lives in spreadsheets on different laptops.
One platform holds every borrower, loan and repayment — no parallel workbooks to reconcile.
Approvals stall because sign-off happens over phone and paper.
A branch → committee → board approval ladder, gated by loan amount, moves each application to the right desk.
Nobody can see portfolio health until month end.
Branch-scoped, role-based dashboards show PAR and portfolio status live, not weeks later.
Field collections are disconnected from the core system.
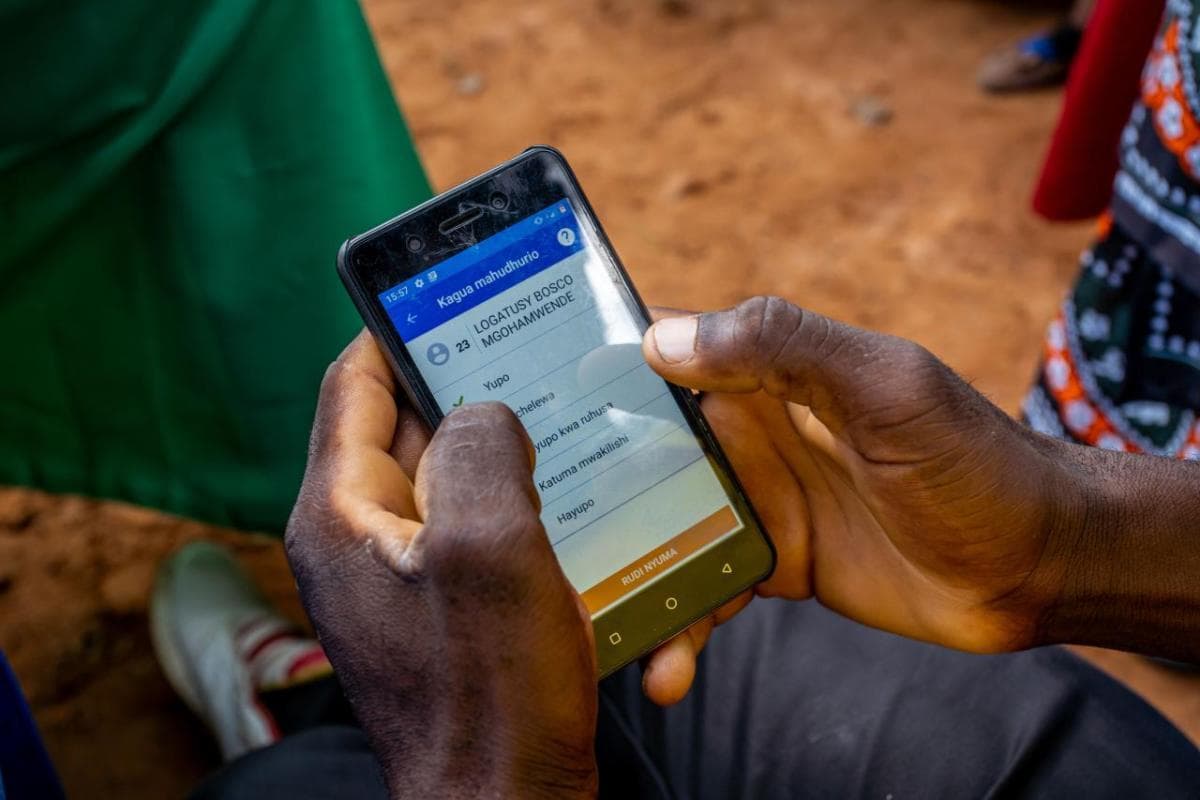
Field officers work an offline-first worklist that syncs collections straight back to the loan.
Month-end reconciliation is a scramble between books.
Every loan event posts to a double-entry GL, so the period closes against books that already balance.
Regulatory reporting is rebuilt from scratch each cycle.
PAR aging and 5-band classification are generated from the ledger, so reports are a view of the books.
Built for how microfinance really works in Tanzania
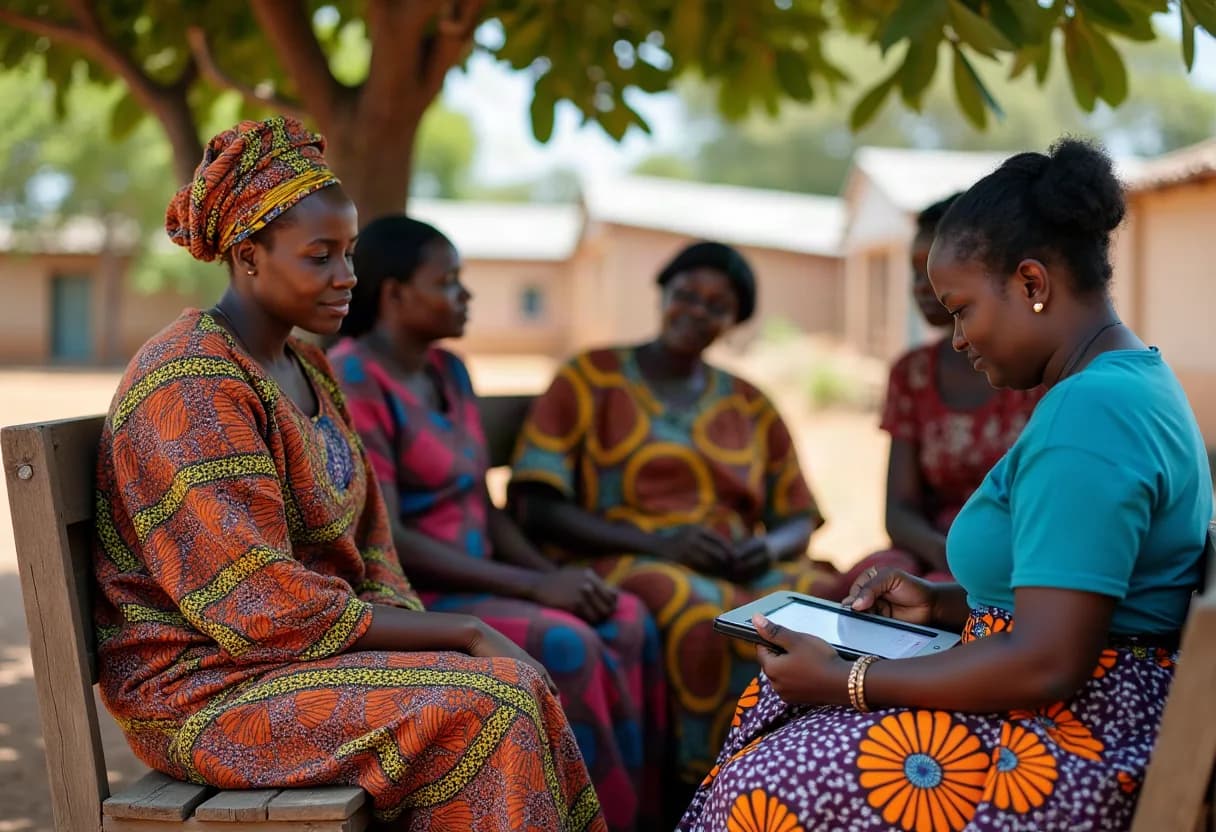
Group collections in the field, savings groups meeting under a tree, ledgers and cash by hand — the realities Ustawi brings onto one platform.
The full loan lifecycle, on one platform
Follow one loan from the branch desk to the board pack. Every stage runs in the same system, so nothing is re-keyed and nothing falls between tools.
Tap a stage to stop on it. Hover pauses the animation.
Switch tabs to explore each view.
The core of an MFI, app by app
The six Ustawi apps an MFI runs every day — and the people at the desk, in the field and in the boardroom who run them.
Loan origination & servicing
Take an application to disbursement and through its whole life on one screen.
- Applications with documents captured at the branch
- The branch → committee → board approval ladder, gated by amount
- Disbursement with automatic double-entry GL postings
- Reducing-balance repayment schedules
- Restructuring and write-offs handled in-system
Collections & delinquency
Turn overdue loans into a worked list rather than a monthly surprise.
- A DPD-driven dunning ladder
- Promise-to-pay capture in the field
- Configurable action ladders per bucket
- Offline-first field worklists that sync on return
- Sync-exception recovery so nothing is lost
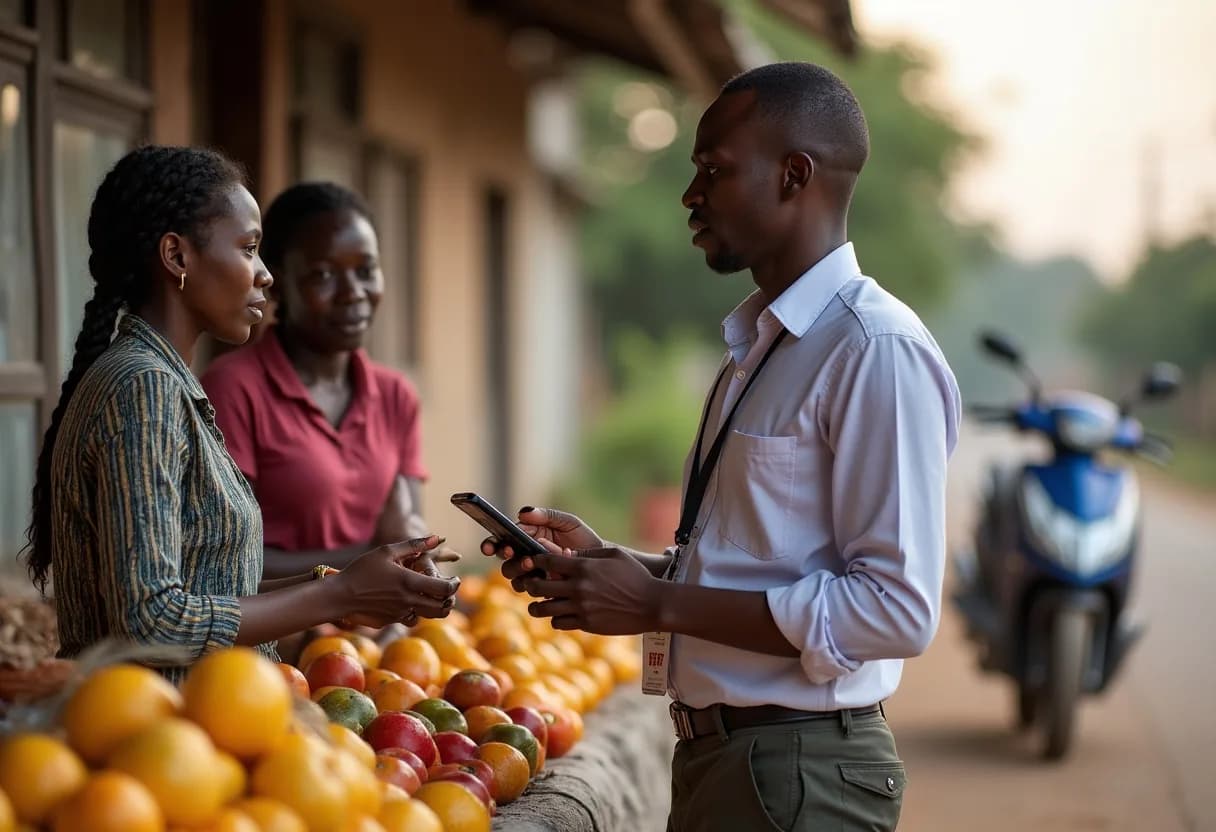
Portfolio & risk — PAR and classification
See portfolio-at-risk and loan classification the way the regulator does, generated from the ledger.
- PAR30 / PAR90 aging generated live
- BOT 5-band loan classification
- Provisioning net of security
- Portfolio disaggregation for the board
- A filings framework for regulatory submissions
Accounting & finance — the general ledger
A real double-entry GL under every loan event, so finance never rebuilds the books.
- Double-entry postings on every loan event
- A configurable chart of accounts
- Trial balance and controlled period close
- VAT treatment mapping
- Loan-linked postings, not manual journals
Compliance & regulatory workflows
Affordability, CRB and recovery workflows built into origination, not bolted on.
- Affordability assessment at application
- CRB checks in the origination flow
- Recovery notices and a complaints register
- BOT-aligned workflows throughout
- An audit trail across sensitive actions
Group lending
Run joint-liability groups on the same engine as individual loans.
- Group loan origination
- Joint-liability servicing
- Group and member views together
- The same GL and reporting as individual loans
- Field-officer worklists for groups
Built for every MFI team
One platform, but each role sees the part of it they run.
Capture applications and run affordability and CRB checks at the counter.
Move applications up the amount-gated committee-and-board approval ladder.
Service live loans, restructures and repayment schedules in one place.
Work a DPD-driven worklist and capture promises-to-pay, offline where needed.
Close the period against a GL that already balances, with no parallel books.
Pull PAR and 5-band classification packs straight from the ledger.
See branch-scoped portfolio health live, not weeks after month end.
Try the approval routing yourself
Start from TSh 12,000,000 over 36 months, then move the amount and watch the approval route and instalment change. Set your own bands to match your credit policy.
Set your own amount bands
18% p.a. reducing balance. Products, rates and bands are configured per institution.
A day in the life
- A branch officer captures an application and runs affordability and CRB checks on the spot.
- Anything above the branch limit escalates up the committee-and-board approval ladder before it can disburse.
- The approved loan disburses and its double-entry GL postings are made automatically.
- Field agents collect against the day's worklist, offline where connectivity fails, and sync on return.
- Finance closes the period against a GL that already balances — no month-end reconciliation scramble.
- The risk team pulls a PAR30/PAR90 and 5-band classification pack straight from the ledger for the board.
Before Ustawi / With Ustawi
Drag the slider: the same loan, kept across branch workbooks versus kept in Ustawi.
| 1956 | Amina Trading | 12,000,000 | ask committee |
| 1955 | Baraka Hardware | 1,150,000 | paid? |
| 1948 | Neema Tailoring | #REF! | collected? |
| PAR30 | all branches | — | ask Juma |
Regulatory & compliance
Ustawi is built to be BOT-aligned: PAR30/PAR90 aging, 5-band loan classification and provisioning are generated from the same ledger the loans run on, and the filings framework structures what you submit. Because the reports are a view of the books, the numbers the board sees and the numbers you file come from one source.
Regulatory treatment can vary by institution type and applicable framework.
Security & data
Access is scoped and every sensitive action is accountable.
- Role-based access control
- Branch-scoped permissions
- Activity and audit tracking
- Secure authentication
- Regular backups
- Controlled admin actions
- Full audit trails
- Data-protection controls
How implementation works
A structured path from first conversation to go-live.
- 01Discovery
We map your products, branches, approval ladder and reporting needs.
- 02Data preparation
Borrowers, loans and balances are cleaned and prepared for migration.
- 03Configuration
Products, amount bands, the approval ladder and the GL are configured to your setup.
- 04Migration & testing
Data is migrated and reconciled, and the workflows are tested end to end.
- 05Training
Each team is trained on the part of the platform they run day to day.
- 06Go-live
You switch over with support on hand, and start closing on balanced books.
Customer story
1,200+ borrowers and 350+ active loans managed on one platform
Read the full story →“We can see each member's loan, repayment history and outstanding balance without searching through multiple books or spreadsheets.”
Apps MFIs typically enable
Applications, the branch→committee→board approval ladder, disbursement, repayment scheduling, restructuring, and write-offs.
Group loan origination and joint-liability servicing.
DPD-driven dunning ladder, promise-to-pay capture, action-ladder config, and sync-exception recovery.
Affordability assessment, CRB checks, recovery-notice controls, complaints register, and compliance evidence in the workflow.
PAR aging, BOT 5-band classification, provisioning, portfolio disaggregation, and the filings framework.
Double-entry GL, chart of accounts, trial balance, period close, and VAT treatment mapping.
Related solutions
Ready to modernize your MFI?
Book a tailored walk-through and we'll show you the workflow end to end.
Frequently asked questions
Yes — see Loan Origination & Servicing and Group Lending.