Collateral & Guarantors
Track, value and govern the security behind every loan.
Register every pledge against the loan it secures, keep its value current, track guarantors as parties in their own right, and keep repossession locked until due process is met.
- Toyota Hiace · COL-00410
- Perfected
- Coverage on loan #1956
- 169%
- Repossession
- Locked until notice served
The real Collateral Register
Close-ups of the live Ustawi portal: the figures a credit team reads first, and what changes when security stops being a list.

- Market valueWhat the active security is worth at its last recorded valuation.
- Forced-sale valueWhat it would realistically fetch in a recovery — the conservative figure.
- PerfectedItems whose charge is registered. The rest are still only pledged.
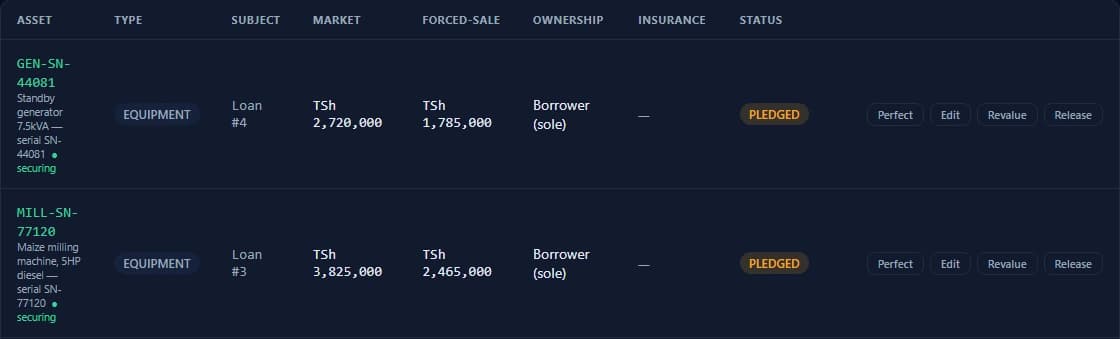
- Two values per itemMarket and forced-sale value sit side by side on every row.
- StatusPLEDGED until the charge is registered, then PERFECTED.
- Act from the rowPerfect, revalue or release an item without leaving the register.
From a spreadsheet to a governed register
Drag the slider: the same security, kept in a workbook versus governed in Ustawi.
| COL-410 | Toyota Hiace | 20,000,000 | valued when? |
| Plot 44 | J. Mbwana | 42,000,000 | charge? |
| Shop stock | Baraka Hdw | #REF! | revalue? |
| Guarantee | R. Mollel | — | ask P. Salum |
One security. One governed lifecycle.
Collateral in Ustawi is not a static list entry — it moves through the same governed stages, from the moment it is registered against a loan to the day it is released or, where it comes to it, recovered.
Tap a stage to stop on it. Hover pauses the animation.
A collateral register you can actually work
Search and filter every piece of security behind the book — each item tied to the borrower and the loan it secures, with its recorded value, status, and next review date in view.
| Collateral | Type | Borrower | Loan | Recorded value | Status | Next review |
|---|---|---|---|---|---|---|
Toyota Hiace — T123 ABC COL-00410 | Vehicle | Amina Trading Co. | #1956 | 19,000,000 | Perfected | 09 Jul 2026 |
Plot 44, Kinondoni COL-00398 | Land & buildings | J. Mbwana | #1902 | 42,000,000 | Perfected | 01 Jul 2026 |
Shop stock — hardware COL-00375 | Inventory | Baraka Hardware | #1888 | 9,500,000 | Revaluation due | 20 May 2026 |
Generator — 40 kVA COL-00361 | Equipment | Nuru Millers | #1854 | 6,200,000 | Verifying | — |
Personal guarantee COL-00344 | Guarantee | Zawadi Saloon | #1830 | 3,000,000 | Recorded | — |
Values in TSh and shown as recorded collateral value — the recognized security value after any haircut and eligibility rules is a separate figure your institution configures.
Every asset has its own complete record
Open a single item and everything about it is in one place — the security details, the documents, its valuation history, the loan it is tied to, insurance, and its verification trail.
The security types your institution uses
From titled land to a personal guarantee, each class of security carries the details that matter to it. Configure the categories your institution actually lends against.
Titled property held as security, with charge references.
Registration and chassis identity, ownership evidence.
Stock and goods, revalued as levels move.
Plant and machinery tied to the loan it secures.
Receivables, deposits and further asset classes.
Third-party guarantees recorded as a form of security.
Value that's kept current, not left to go stale
A collateral value is only useful if it's current. Revaluation is a formal, recorded workflow — each new figure keeps its source and date, and sets the next review.
- 09 Jan 2026Initial valuationTSh 20,000,000
- 09 Apr 2026Formal revaluation−5.0%TSh 19,000,000
Revaluation cadence and who may value are configurable. Recorded value is not automatically the recognized security value — haircuts and eligibility rules apply per your institution's policy.
Coverage against what's still owed
See recorded collateral value against the outstanding balance at a glance — with a clear note that recognized security value can differ from recorded market value.
Try the coverage check yourself
Move the recorded value and the balance and watch loan #1956's coverage against a minimum you set.
Set your own coverage minimum
Coverage = recorded collateral value ÷ outstanding balance. Recognized value, haircuts and coverage minimums are configured per institution.
The paperwork behind the security, in one place
Each item can carry the documents that make it real security — ownership evidence, valuation, charge registration, insurance. A simple checklist shows what's complete.
- Ownership evidenceRegistration card on file
- Valuation reportDated 12 Feb 2026
- Charge / lien registrationReference recorded
- Insurance certificateCover current
- Photographs of assetUploaded at verification
Required documents are configured per security type.
Collateral status lifecycle
As an item moves through its life, its status moves with it. Status names and transitions are configured by your institution.
Releasing security once the loan is settled
When a loan is fully repaid, releasing its security is itself a governed step — requested, approved, actioned and recorded, so the discharge is never an untracked change.
Release approval follows the mandates your institution configures.
A complete, auditable history
Every material action on a piece of collateral — registered, verified, valued, revalued, released — is captured with the actor and the timestamp, ready for an auditor's question.
- Collateral registered against loan #1956J. Mushi (Loan Officer)08 Jan 2026 · 09:22
- Ownership verified & documents attachedJ. Mushi (Loan Officer)08 Jan 2026 · 14:05
- Initial valuation recorded — TSh 20,000,000P. Salum (Credit)09 Jan 2026 · 10:40
- Charge registered — perfectedR. Kessy (Branch Manager)13 Jan 2026 · 16:12
- Revaluation recorded — TSh 19,000,000P. Salum (Credit)09 Apr 2026 · 11:03
Guarantors, recorded as parties
Guarantors are parties in their own right
A guarantor is not a note on the borrower's file. They're recorded as a distinct party — with their own details, the loan they stand behind, the amount guaranteed, and their obligations.
- Guarantees the loan up to the recorded amount
- Obligation stands until the loan is settled or released
- Recorded and tracked separately from the borrower
Guarantor exposure at a glance
Because guarantors are tracked as parties, you can see exposure across the book — how many stand behind loans, how much is guaranteed, and where the same name recurs.
Recovery only after due process
Repossession stays locked until due process is met
Recovery is never a button an officer can just press. Repossession is hard-gated: it stays locked until a recovery notice is served through Compliance and the required period has elapsed.
- Recovery requestedDone
Raised against the loan when it falls into default
- Recovery notice servedGate
Issued and served via the Compliance app — the hard gate
- Required period elapsesGate
The applicable notice period must pass
- Recovery action availableAvailable
Only now can repossession be actioned
Wired into Compliance & Regulatory
The recovery gate isn't a checkbox inside Collateral — the notice is issued and served in the Compliance app, and only that served notice unlocks recovery back here.
See the recovery gate working on your own book.
The whole book, not just one item
Monitoring that surfaces what needs attention
Instead of discovering a stale value or a lapsed cover during an audit, exceptions are surfaced as they arise — revaluations due, documents expiring, coverage gaps, and recovery cases.
| Collateral | Loan | Exception | Priority |
|---|---|---|---|
| COL-00375 · Shop stock | #1888 | Revaluation overdue by 14 days | Medium |
| COL-00298 · Plot 12, Mbezi | #1771 | Coverage below policy minimum | High |
| COL-00252 · Nissan Canter | #1699 | Insurance certificate expiring | Medium |
The collateral portfolio, at a glance
Above the individual items sits the portfolio view — how much security backs the book, how much is perfected, and how it splits by type.
- Land & buildings46%
- Vehicles24%
- Inventory14%
- Equipment10%
- Guarantees & other6%
Connected to the loan and the platform
Security is bound to the loan, not filed beside it
Collateral and guarantors are recorded against the loan they secure — so the loan record always knows what stands behind it, and each item knows which loan it protects.
| Item | Type | Value | Status |
|---|---|---|---|
| Toyota Hiace — T123 ABC | Vehicle | 19,000,000 | Perfected |
| Personal guarantee — R. Mollel | Guarantee | 5,000,000 | Recorded |
Values in TSh. Recorded collateral value shown.
Guarantors are recorded as a separate party linked to the loan — distinct from the borrower.
Connected across the Ustawi platform
Collateral & Guarantors doesn't stand alone. The apps around it share the same loan record — the collateral you register here is the security the rest of the platform reasons about.
Collateral and guarantors are captured against the loan record.
Explore app →Recovery notices are issued and served here — the repossession gate.
Explore app →Asset-insurance cover sits alongside the collateral it protects.
Explore app →Overdue loans drive the cases where recovery is raised.
Explore app →Recovery and release outcomes flow through to the books.
Explore app →Security that protects a real relationship
Behind every collateral record is a borrower and a loan officer agreeing what stands behind the loan. Governing that security well — valuing it, documenting it, and following due process on recovery — is how a lender stays fair to the borrower and safe on the book at the same time.
- Loan officers
- Credit & risk teams
- Branch managers
- Auditors & compliance
Getting live
How we get you live
A structured rollout, from mapping your security policy to governing collateral on Ustawi.
- 01Discover
Map the security types you lend against and your recovery process.
- 02Configure
Set collateral categories, required documents, and review cadences.
- 03Migrate
Bring existing collateral and guarantor records onto the platform.
- 04Test
Validate coverage, revaluation, and the recovery gate against known cases.
- 05Train
Bring officers, credit, and compliance staff up to speed.
- 06Go live
Register and govern security on new and existing loans, with support on hand.
See Collateral & Guarantors in a live demo
Request a DemoFrequently asked questions
No. Repossession is hard-gated: it stays locked until a recovery notice is served through the Compliance app and the required period has elapsed. The workflow is enforced by the system, but the notice, the period, and any recovery action remain subject to the applicable legal/regulatory framework and your institution's own process.